To better understand how confident beauty professionals and beauty schools feel about their businesses, the Professional Beauty Association (PBA), in partnership with PBA Business Member Pivot Point International, created the Pro Beauty Pulse.
This monthly index tracks industry sentiment across W-2 beauty professionals, independent professionals, salon owners, and beauty school leaders. We also include data from The KIM Report, providing real-world salon performance results to complement sentiment insights.
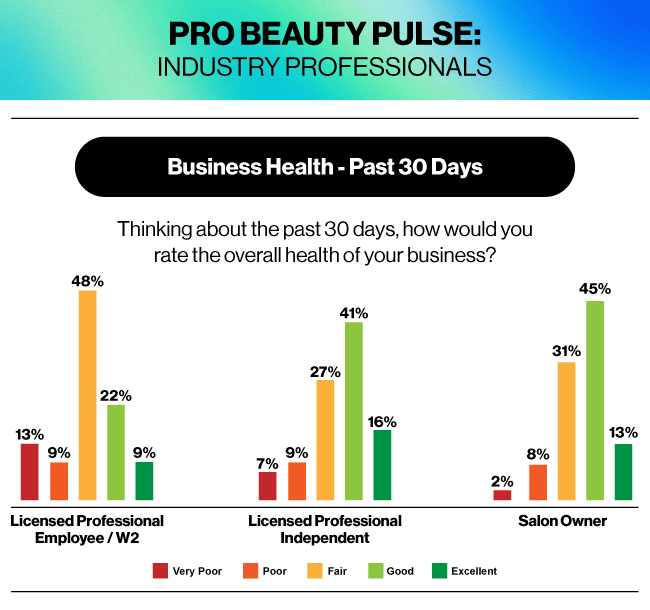
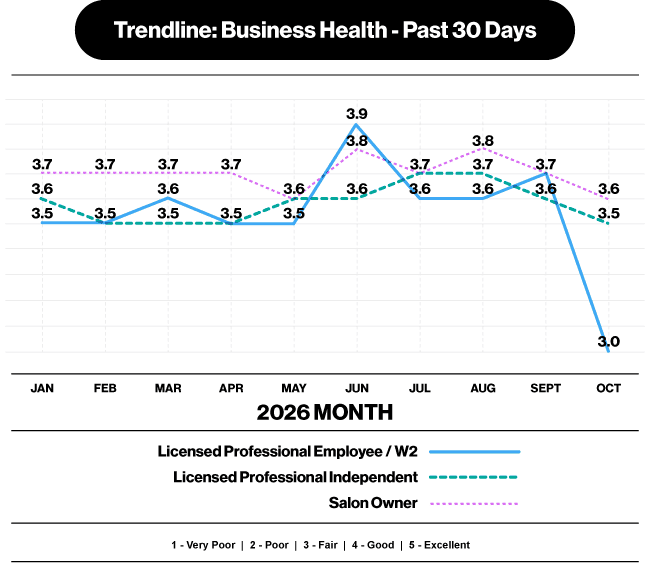
PERCEPTION VS. REALITY
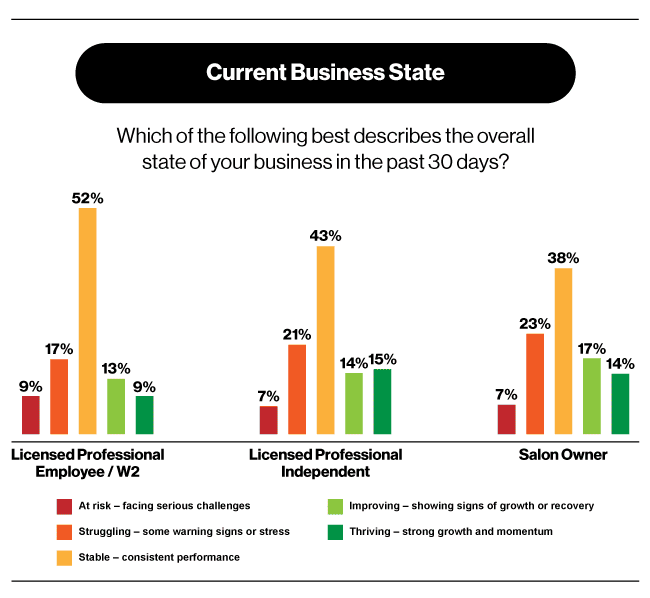
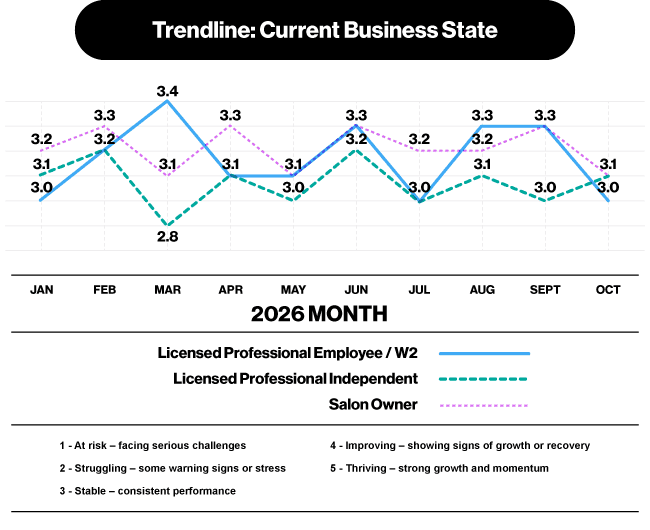
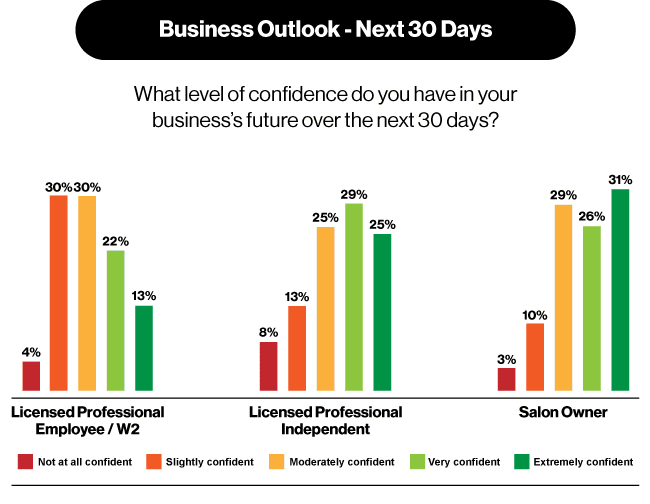
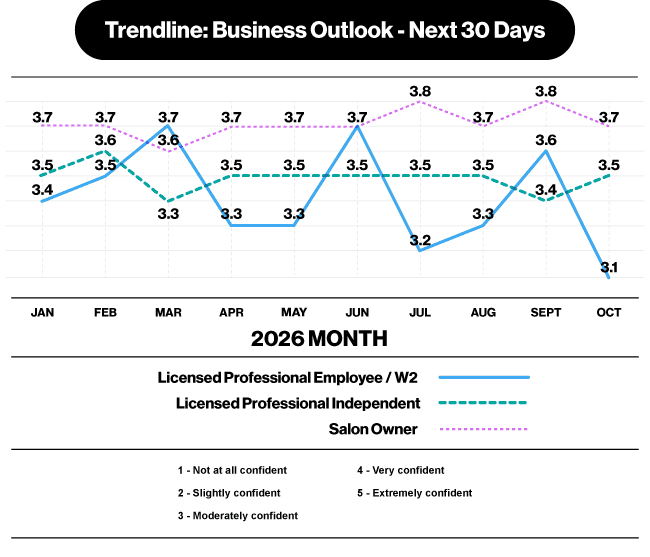
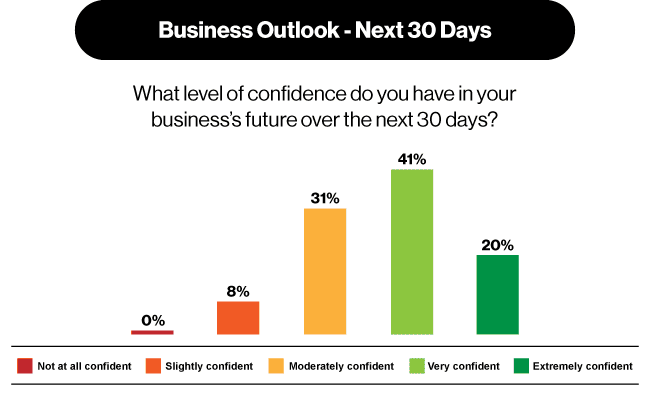
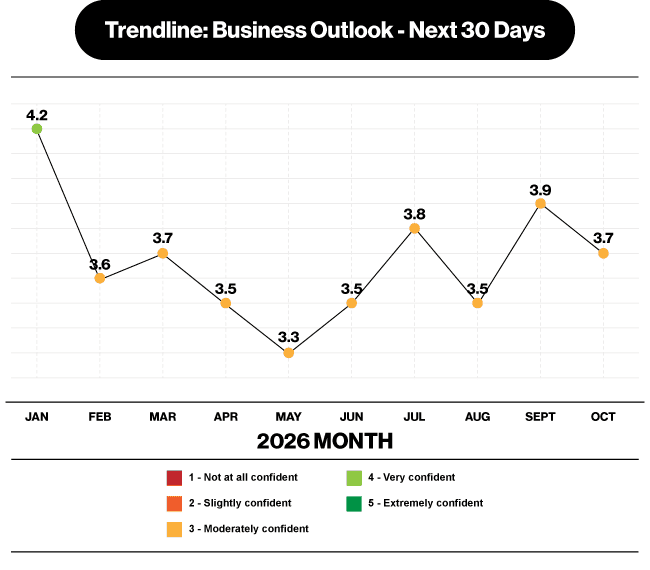
The charts above reflect sentiment collected in October when industry professionals were asked to assess their business conditions for September.
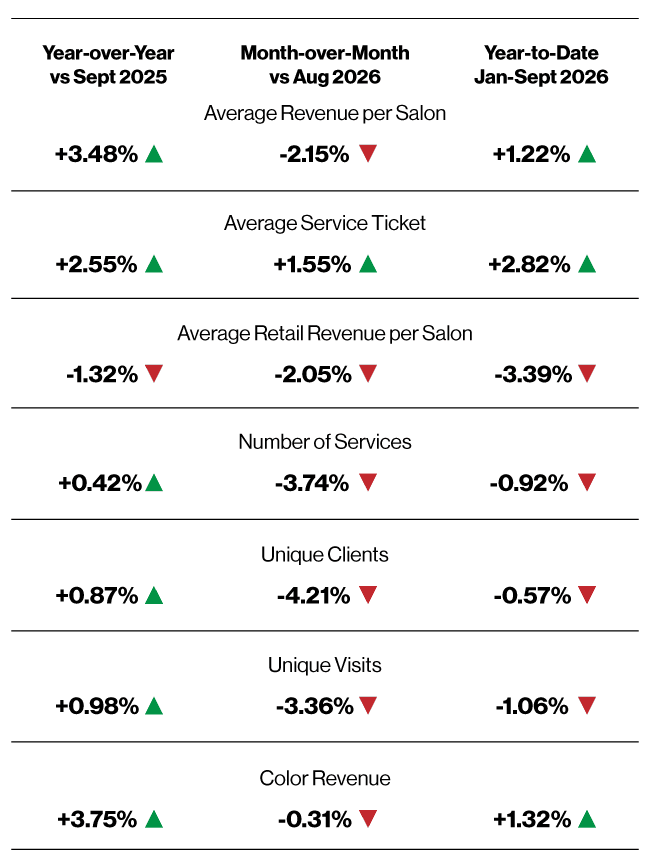
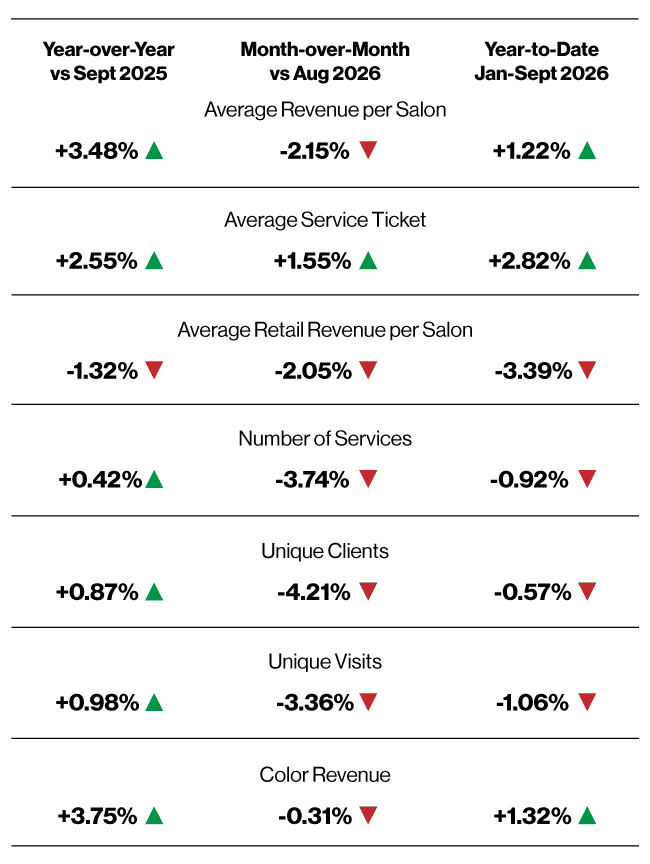
The data below, sourced from The KIM Report, shows actual industry performance for September.
Viewed together, these offer a comparison of how salon industry perceptions compare to salon industry results.
KEY TAKEAWAYS:
Month-over-month actuals for September declined on most measures against August, this was reflected in the decline in confidence across all three pro market categories (employees, independent, owners).
However, year-to-date, average salon revenue remains 1.22% above 2025 levels. Higher service prices are helping: the average ticket is up 2.82%. Services, clients, and visits remain slightly below last year.
Smaller salons are struggling while larger salons are growing. Revenue fell 2.30% at salons with one or two stylists. It rose by 1.94% at salons with three to four stylists and by 5.50% to 6.51% in the larger groups.
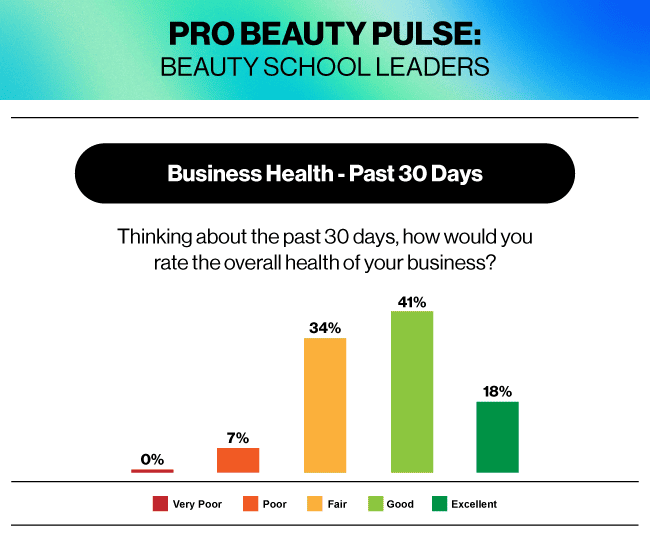
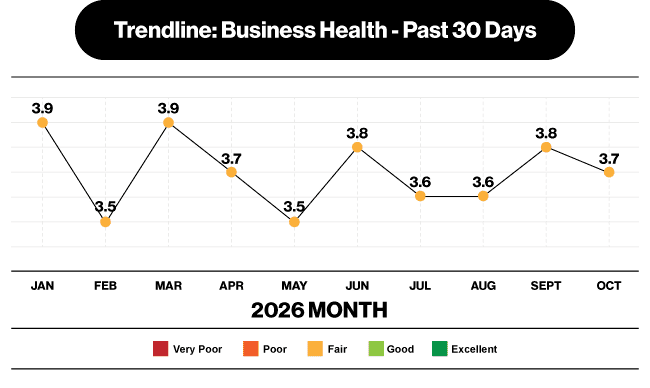
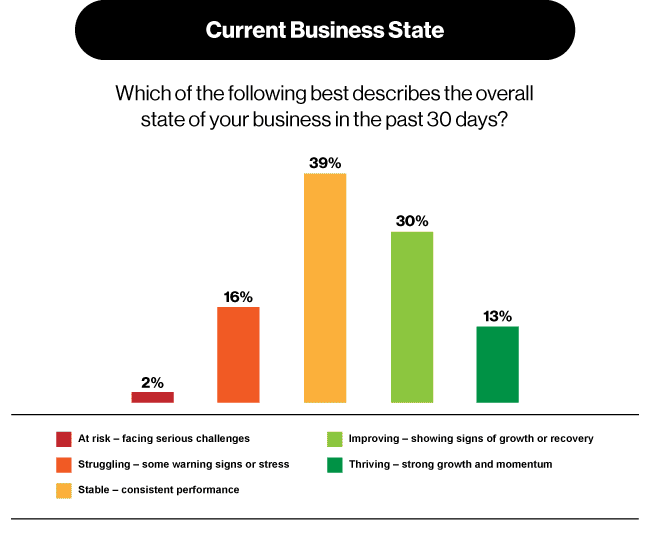
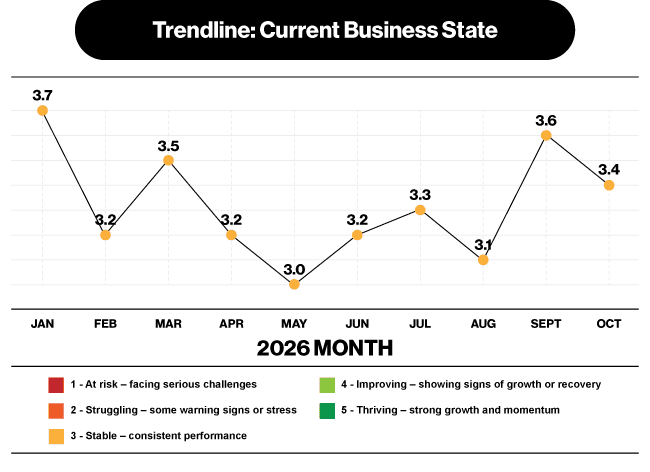
KEY TAKEAWAYS:
Overall, school confidence dipped slightly across all three measures in October vs. September.
The KIM Report aggregates data from more than 10,000 salons and solopreneurs, each with 24 consecutive months on the same software platform to ensure data consistency and reliability.
September returned to positive year-over-year growth, with average revenue per salon up 3.48% compared with September 2025. Unlike August, the improvement was supported by both pricing and activity. The average service ticket increased
2.55%, while services (+0.42%), unique clients (+0.87%) and visits (+0.98%) all moved back into positive territory.
The month-over-month decline from August is broader, with revenue down 2.15%, services down 3.74%, visits down 3.36% and clients down 4.21%. However, the average service ticket increased 1.55%, helping offset some of the
lower activity.
Retail remains the most challenged part of the salon business. Retail revenue declined 1.32% year over year, while units sold were down 7.86%. A roughly 7.10% increase in the average product price continued to cushion the impact of
lower unit volume.
Color was again a strong performer. Color revenue increased 3.75% year over year, supported by a 1.64% increase in color services. Year-to-date, color revenue is now 1.32% ahead of 2025.
Performance by salon size continues to diverge significantly. Salons with one to two stylists were down 2.30% year over year, while every larger cohort grew. Revenue increased 1.94% among three- to four-stylist salons, 5.50% among five to
nine-stylist salons, 6.51% among 10- to 19-stylist salons and 6.14% among salons with 20 or more stylists. The K-shaped pattern in salon performance is becoming increasingly difficult to ignore.
Year-to-date, average salon revenue is now 1.22% ahead of 2025. Pricing remains an important contributor, with the average service ticket up 2.82%, while services, clients and visits remain slightly below last year.
STAY INFORMED
Explore more insights in The KIM Report, your source for real-world data and monthly performance trends shaping the professional beauty market.